24/7 Emergency Does Homeowner Insurance Cover Sewer Backup & Drain Overflows?
Standard homeowner insurance policies typically exclude damage caused by sewer backups and sump pump overflows unless the policyholder purchased an optional Water Backup and Sump Discharge endorsement. This endorsement provides dedicated coverage for biohazard cleanup, water extraction, and structural repairs.
Our field restoration engineering network answers critical questions regarding emergency structural drying, insurance claim line items, and IICRC S500 procedural standards to assist homeowners facing indoor water crises.
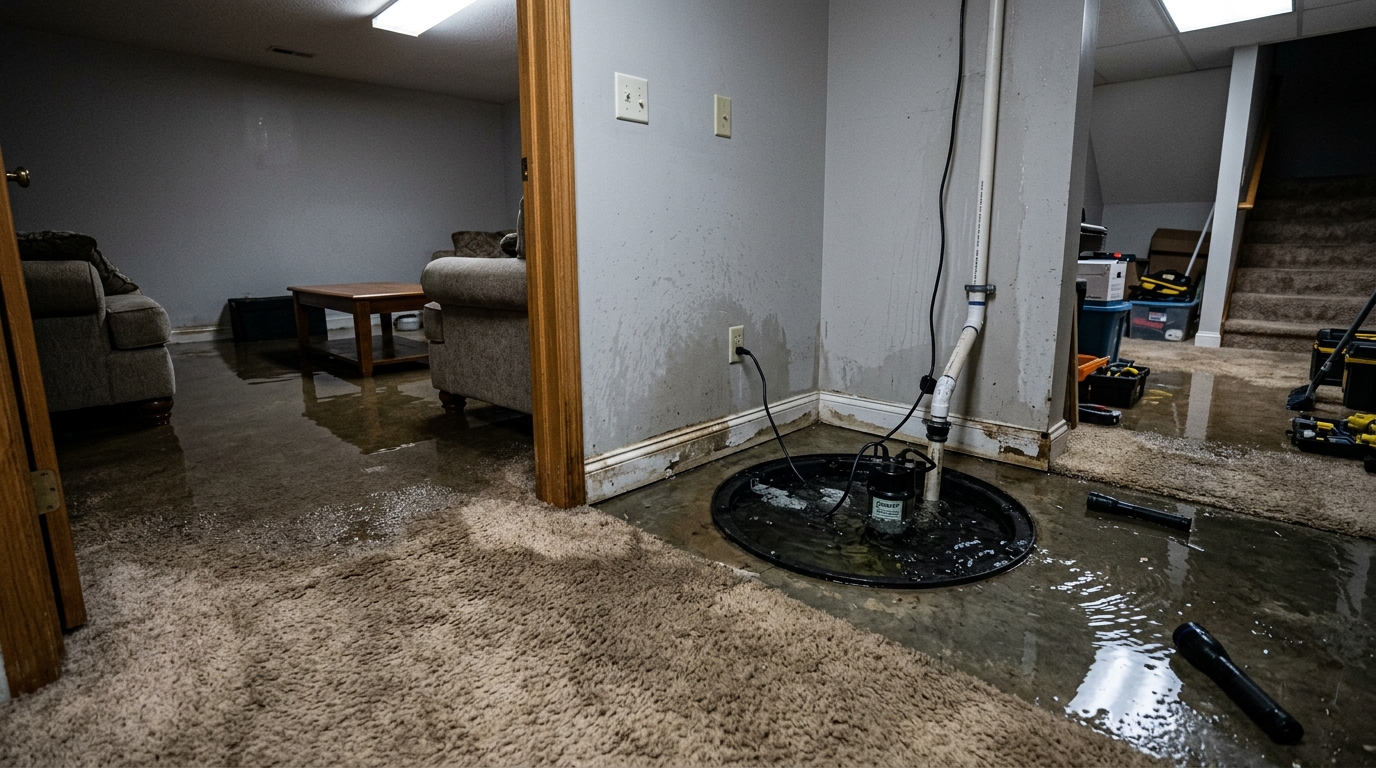
Standard Policy Exclusions vs Optional Backup Endorsements
A common point of frustration for homeowners following an indoor sewage disaster is discovering that standard HO-3 homeowner insurance policies exclude drain overflows. Securing proper endorsement riders before emergencies occur ensures financial protection against severe losses.
The Standard Water Damage Exclusion Clause
Standard homeowner insurance policies cover sudden and accidental internal plumbing line ruptures, such as burst copper supply pipes. However, policies specifically exclude water that backs up through sewers or drains or overflows from a sump pump basin under standard terms.
Without an optional endorsement, homeowners must pay for biohazard remediation out of pocket. Adding water backup coverage costs relatively little per year.
Water Backup and Sump Discharge Endorsement Limits
Adding an optional Water Backup endorsement provides specified coverage limits ranging from $5,000 to $25,000 or more for sewage cleanup, drywall demolition, and personal property replacement. This rider covers both municipal sewer surges and mechanical sump pump failures.
Homeowners with finished basements should secure at least $20,000 in endorsement limits. Commercial biohazard remediation for sewage backups often exceeds $7,000.
Documenting Sewer Backup Damage for Insurance Adjusters
Successfully settling an insurance claim for sewer backup water damage requires meticulous documentation of contaminated building materials and personal belongings. Restoration specialists assist homeowners by providing standardized Xactimate line items and photographic proof.
Date-Stamped Photographic & Video Documentation
Before technicians remove contaminated building finishes or discard ruined furniture, take clear date-stamped photographs and video recordings of standing sewage levels and stained baseboards. Detailed visual records provide conclusive proof of loss for insurance claims adjusters.
Avoid throwing away damaged electronics or furniture before adjusters inspect them. Technicians compile comprehensive non-salvageable personal property loss inventories.
Itemized Xactimate Line Items & Psychrometric Logs
Restoration contractors utilize industry-standard Xactimate pricing software recognized by all major property insurance carriers. Itemized billing accounts for square footage extracted, equipment runtimes, drywall flood cuts, and antimicrobial treatments.
This standardized formatting streamlines insurance claim processing and minimizes out-of-pocket friction for policyholders.
Municipal Sewer Main Backups vs Private Drain Line Clogs
Determining whether a sewer backup originated within city main sewer lines or your private residential sewer lateral affects legal liability and potential municipal reimbursement claims. Understanding jurisdiction boundaries clarifies insurance recovery paths.
Municipal Combined Storm-Sewer Surges
Intense torrential rainstorms can overwhelm municipal combined storm-sewer infrastructure, forcing raw sewage backward through residential basement floor drains and lowest-level toilets. In some jurisdictions, cities offer limited liability reimbursement programs for storm surges.
Homeowners must file municipal claims within strict statutory notice windows. Private insurance backup endorsements provide faster immediate relief.
Private Sewer Lateral Root Intrusion & Blockages
Property owners are legally responsible for maintaining the private sewer lateral connecting their home foundation to the municipal sewer main in the street. If tree roots or aging cast iron pipes collapse within private property lines, the homeowner is responsible.
Licensed drain contractors perform fiber-optic sewer camera inspections to confirm blockage locations. Hydro-jetting clears root obstructions before future backups occur.
Permanent Prevention: Installing Backwater Check Valves
Protecting finished basements and ground-floor bathrooms from recurring municipal sewer surges requires installing an automatic backwater prevention check valve on the main residential sewer lateral. These mechanical valves lock out external municipal floodwaters permanently.
Automatic Flapper Sealing During City Storm Surges
Backwater valves feature balanced internal mechanical flappers that allow household wastewater to flow outward toward the municipal sewer main while sealing shut automatically when city sewers surcharge backward under storm pressure.
Installing backwater valves eliminates sewer backup vulnerabilities permanently. Many insurance carriers offer policy discounts for homes with installed valves.
Annual Maintenance & Cleanout Valve Inspection
Backwater valves require annual inspection through access cleanout ports to ensure that toilet paper residues or mineral build-up do not impede flapper movement. Flushing valves with clean water guarantees reliable emergency sealing during severe weather events.
Restoration specialists advise property owners on local plumbing code requirements. Backwater protection preserves valuable finished basement living spaces.
Frequently Asked Questions: Does Homeowner Insurance Cover Sewer Backup & Drain Overflows?
Review authoritative answers to common homeowner questions regarding restoration timelines, equipment operation, and insurance documentation.
No. Standard homeowner insurance policies exclude sewer backups and sump pump overflows. Coverage requires an optional W...
No. Standard homeowner insurance policies exclude sewer backups and sump pump overflows. Coverage requires an optional Water Backup and Sump Discharge or Overflow endorsement rider.
A water backup endorsement typically costs between $35 and $100 per year, providing between $5,000 and $25,000 or more i...
A water backup endorsement typically costs between $35 and $100 per year, providing between $5,000 and $25,000 or more in dedicated biohazard cleanup and structural repair coverage.
Cities are generally not liable unless the homeowner proves municipal negligence in sewer line maintenance. Filing throu...
Cities are generally not liable unless the homeowner proves municipal negligence in sewer line maintenance. Filing through your private water backup policy endorsement is typically the fastest path to recovery.
Installing an automatic backwater prevention valve on your main sewer lateral allows domestic wastewater to exit while s...
Installing an automatic backwater prevention valve on your main sewer lateral allows domestic wastewater to exit while sealing automatically to block municipal sewage surges from entering.
Call our 24/7 emergency referral hotline now to check on-call restoration capacity in your local municipal area.
📞 CALL (855) 716-3231